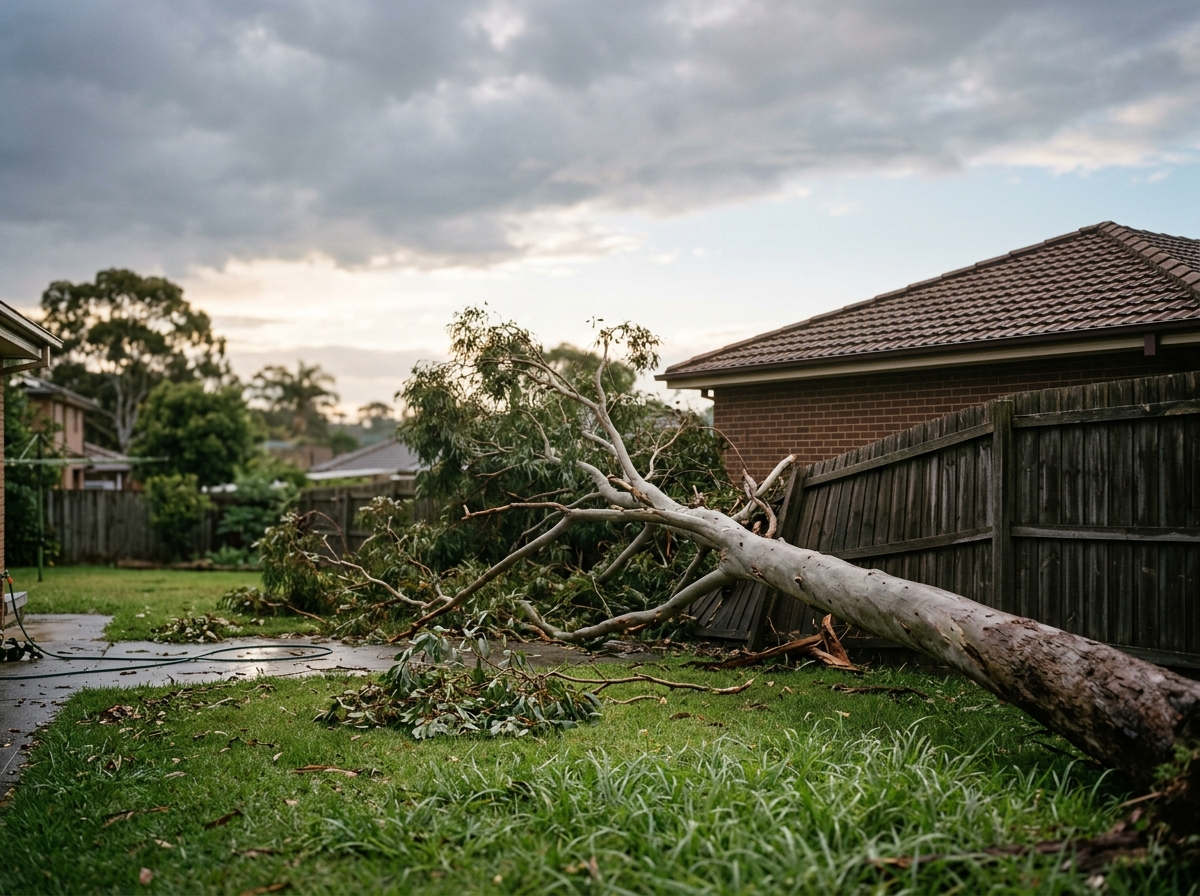
Insurers separate sudden damage from ongoing upkeep. A storm-damaged tree that lands on your roof is an insured event. A dead, diseased or overgrown tree that has not fallen is usually maintenance, and that stays with the homeowner.
Preventative pruning, routine tree care and inspections generally fall outside cover. So does tree removal where nothing has been damaged and no immediate hazard exists. If a tree is leaning, rotting or too close to the house, arranging tree removal before it fails is typically your cost.
The outcome comes down to two things: the cause of the fall and the exact wording of your home insurance policy. Policies vary, so check your product disclosure statement or ask your insurer directly. This is general information, not financial or legal advice.
If a tree is already down or looks unsafe, do not wait on the paperwork. Call 0475 463 597 any time, and the team can make the site safe and note what happened to support your claim.