Insurers typically assess a fallen tree claim on three things: a clear cause, visible damage or safety risk, and whether the policy limits cover the work. Trees Down Under keeps the money and paperwork side simple so owners can focus on their home.
What insurers typically look for
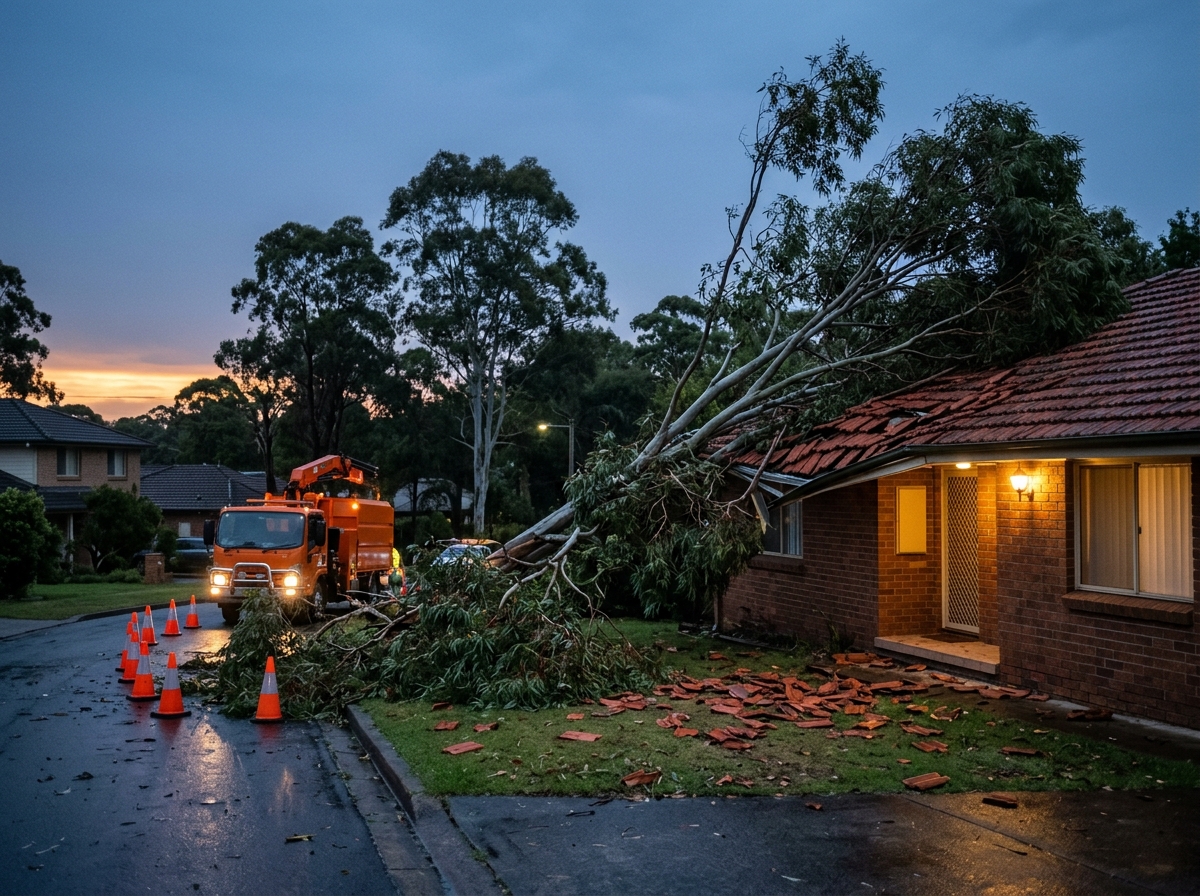
Most insurers want a clear cause, such as severe wind, a storm cell or lightning, and evidence the tree fell during that event. Cover is not certain, so check your policy wording or ask your insurer.
- A tree or limb on your home, garage, fence or carport
- Broken roof tiles, gutters or windows, or water entering the house
- A tree blocking the only safe exit route
- A hung-up limb over a bedroom, footpath or vehicle
Caps on debris removal and tree cutting
Many policies apply sub-limits to debris removal and tree cutting, particularly where there is no building damage. Some pay for repairs but only a small benefit for tree work. Knowing your limit before work starts avoids surprises.
Quotes and paperwork without the headache
Quotes are itemised upfront, with no hidden fees and no extra crane charge, because the crane fleet is Trees Down Under’s own. The quote includes full site clean-up and green waste disposal, and the team provides the documentation insurers ask for. Where a council permit or arborist report is needed, it is handled for you.
We work with every local council in Sydney. Permits and paperwork don’t have to be a headache for the homeowner.
Joseph Khoury, Director & Founder, Trees Down Under